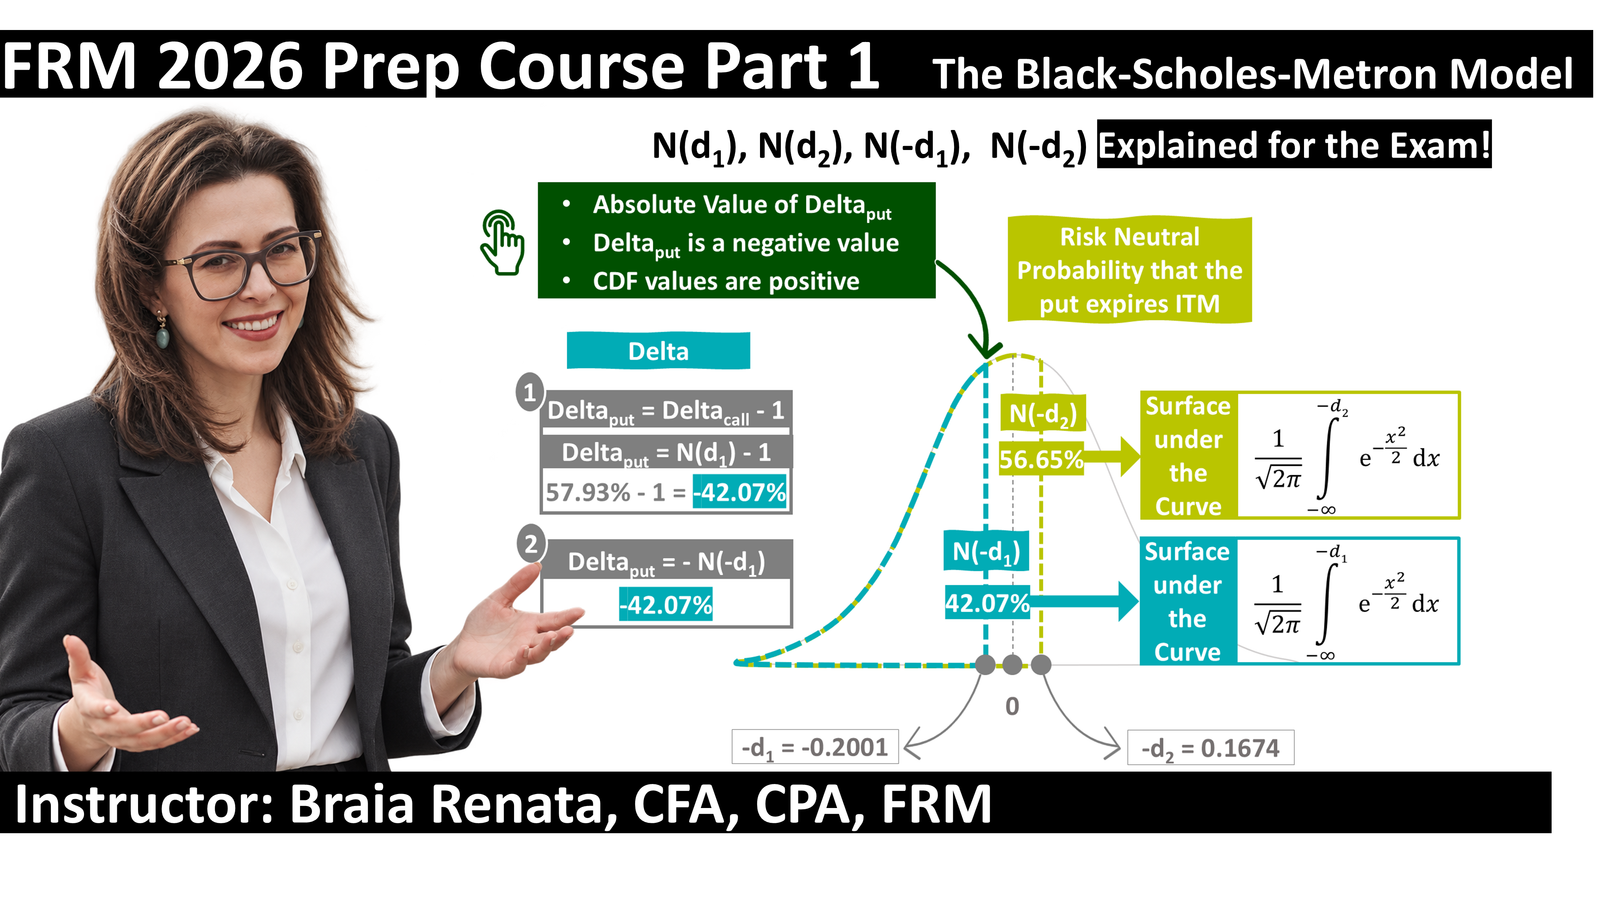
FRM Part 1 Prep | Black Scholes Pricing Model – N(d1),N(d2),N(-d1) & N(-d2) Explained
Black-Scholes-Merton Model: A Step-by-Step Pricing Example Given the underlying asset price, strike price, risk-free rate, volatility, and time to maturity, we can calculate the value of European call and put…